Property Explainers
What Is ABSD? Additional Buyer's Stamp Duty, Explained Simply
2 min read
The loan covers the largest line, so people assume the rest is small. It isn't. Here is every cash and CPF outlay in an upgrade, in the order you will be asked for it — the same whether you are selling an HDB flat, an EC or a condo.
Licensed real estate salesperson · CEA Reg. No. R059523G
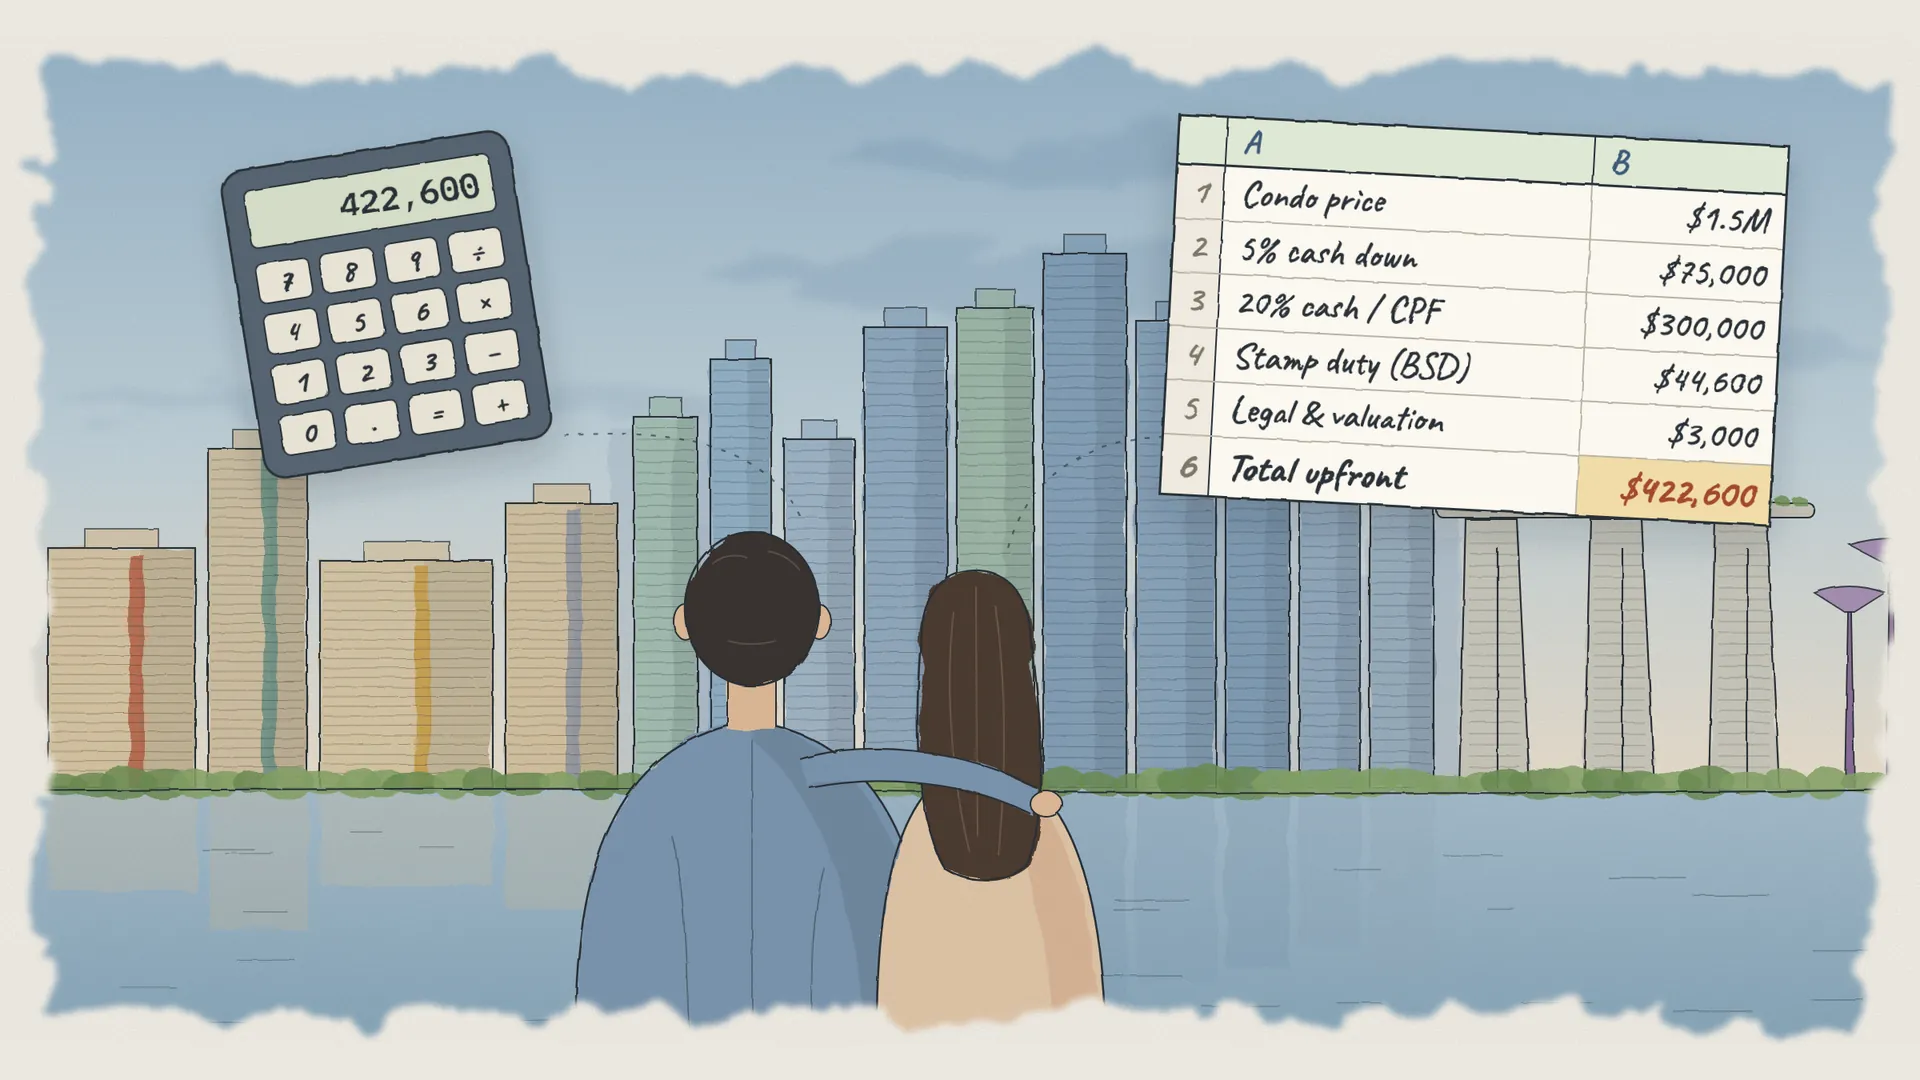
The mortgage covers the biggest line on the page, so it is natural to assume everything else is rounding. In practice, the non-loan portion of an upgrade is where households get caught — not because any single item is enormous, but because there are seven of them and they arrive close together.
The short answer
Almost every misunderstanding in this area comes from treating "money I have" as one pool. It isn't. It is two pools with different rules.
CPF can be used for a large part of the purchase, subject to limits, and it is where most of your sale proceeds will land, whether you are selling a flat, an EC or a condo. Cash is required for a defined minimum portion of the downpayment, and for most of the smaller costs — and is the only pool that helps you if something goes wrong.
An upgrader can be CPF-rich and cash-poor, and still fail a purchase that looks perfectly affordable on a summary page.
The working question
Not "can we afford this?" but "on the day each payment falls due, will the money be in the right pool?"
To secure a unit, you pay an option fee. For a resale purchase this is typically 1% of the purchase price, paid in cash on the spot. For a new launch, a 5% booking fee is paid at the point of booking.
Upon exercising the option in the law firm, the balance 4% of the cash downpayment is due and that timeline is typically within 14 days for resale. Missing it can cost you the option fee being forfeited by the seller, so this is not a deadline to manage casually.
A housing loan covers up to 75% of the price. Of the 25% downpayment, 5% has already gone out as the option fee and the exercise payment, so a further 20% falls due here, split between cash and CPF.
Loan limit as at September 2026
The 75% loan-to-value limit above applies to a first housing loan and has been revised before. It is lower if you already hold an outstanding housing loan, which raises the cash and CPF you need upfront. Check the current limits with MAS or your banker.
BSD applies on every residential purchase, calculated on tiers of the purchase price or market value. It is due within 2 weeks after the document is signed and has to be paid upfront in cash first for resale.
If you will hold more than one residential property at the point of purchase — which is exactly the situation of anyone buying before selling — ABSD applies on top of BSD, at a rate that depends on residency status and property count.
This is the single largest swing factor in an upgrade budget. What ABSD is, and when it applies, is covered here.
Rates change, and they matter here
BSD tiers and ABSD rates have both been revised more than once. Anything you read online — including this article — could be out of date on rates. Check the current schedule on the IRAS website before you build a budget around it.
Conveyancing, valuation, mortgage stamp duty and property tax.
For a resale unit, this is often the largest cash item after the downpayment — and the one most likely to run over. For a new launch, it is smaller and deferred.
Not a cost, but it belongs in the same budget. Everything above is the price of getting in. The buffer is the price of being able to stay in comfortably if an income pauses, a rate rises, or something entirely unrelated to property goes wrong in your life.
Day 0
Option fee
1% paid in cash when you secure the unit, in exchange for the Option To Purchase (OTP)
Day 14 / Week 2
Exercise the option
4% paid in cash to exercise the option at the law firm.
Week 4
Stamp duties
BSD, and ABSD where it applies. Due within 2 weeks after exercising.
Week 10–14
Completion: 20% balance, fees, keys
Typically 8–12 weeks from exercising the OTP. Remaining cash and CPF, maintenance fees, then renovation begins.
Indicative sequence for a resale purchase. New launches follow a progressive payment schedule instead. Speak to your real estate salesperson or conveyancing lawyer to confirm.
You are selling first. Your CPF refund returns to CPF, and your cash proceeds return to you. That usually solves the CPF side of the next purchase and leaves cash for the rest — provided the timing lines up. However if your purchase completes before your sale does, you need the cash or bridging loan or both, for whatever that's coming.
You are buying first. Add ABSD to the upfront requirement, work with the lower loan-to-value limit, and plan for two sets of monthly payments for a period. If the remission applies to you, treat the refund as something that arrives later.
Work out every payment, put a date next to each one, and check that your cash buffer survives the whole timeline — then go and look at property.
Last updated 29 September 2026Based on publicly available Singapore property data
Sources & where to verify
Rules, rates and published figures change. Check the current position on the official source before you act on anything here.
New insights, when they're worth sending
Occasional emails when I publish something useful. No listings, no blasts.
Where most people go next from here.
I'd like to measure which articles are actually useful, using Google Analytics and a Meta advertising pixel. Nothing is loaded until you choose, and declining costs you nothing on this site. What these do.