Upgrading
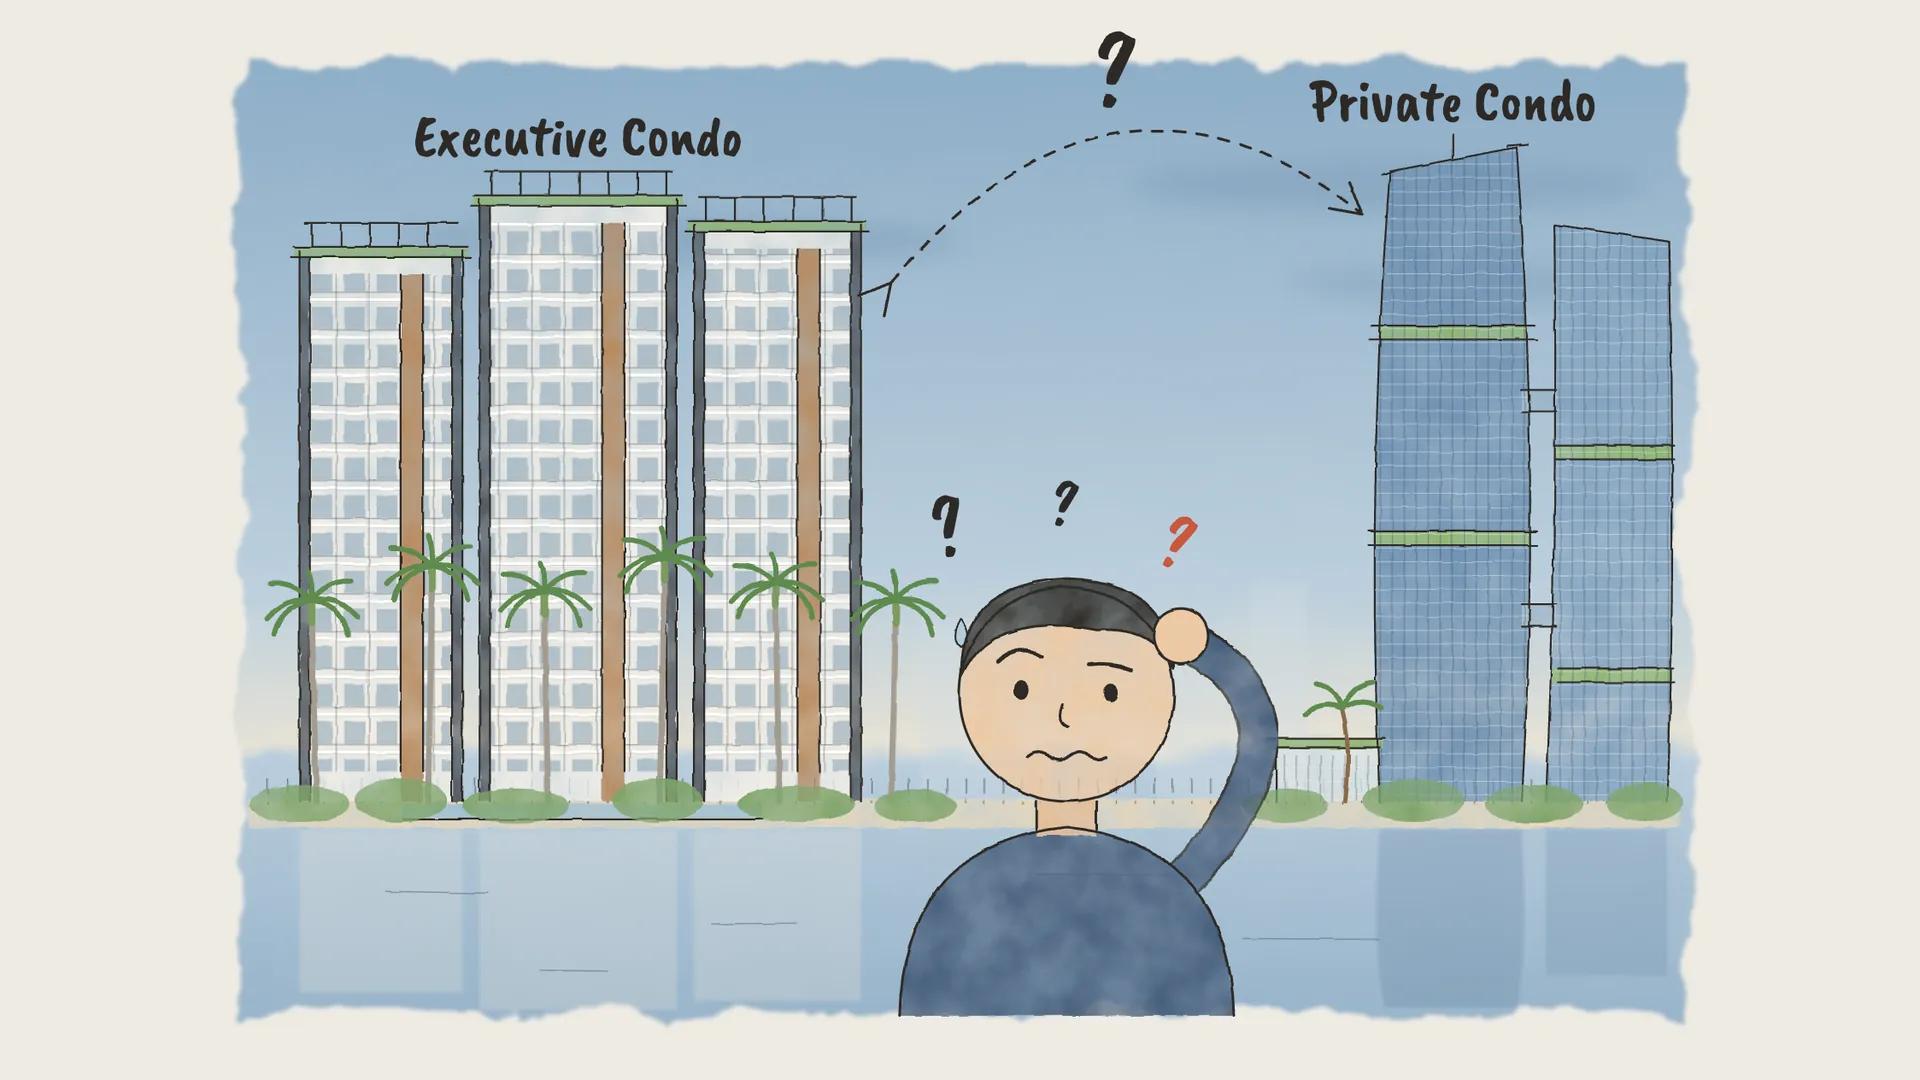
EC vs Private Condo: What's The Actual Difference?
4 min read
Four paths open up the moment your EC becomes sellable — sell and upgrade, sell and right-size, hold and stay, or decouple and buy a second property. Here is how to tell them apart.
Licensed real estate salesperson · CEA Reg. No. R059523G
Five years pass faster than anyone expects. Then the MOP ends, the market chatter starts, and a lot of EC owners feel a vague pressure to do something — usually without a clear sense of what the something is for.
Here is the honest map.
The short answer
Two things. You can now sell — to Singapore Citizens and Permanent Residents, until the ten-year mark, after which the unit is fully privatised. And any CPF you have used is now potentially recoverable for another purchase, via a sale.
That is it. Nothing about your financial position changed overnight. What changed is the option set.
The most common instinct, and sometimes the right one.
You sell, your outstanding loan is repaid, your CPF is refunded with accrued interest, and what remains funds a larger or better-located private property.
Works well when: you have genuinely outgrown the space, the location no longer fits (schools, work, family), and the numbers on the next purchase leave you a buffer.
Works badly when: the driver is a feeling that you should be moving up rather than a specific problem being solved. Upgrading into a tighter monthly position to gain two hundred square feet is a poor trade.
Less discussed, and underrated.
Some households find that the EC was the right property for a stage that has passed — children have moved out, or work has relocated, or the maintenance and commute no longer earn their keep. Selling into something smaller or better located, and freeing up capital, is a legitimate move rather than a retreat.
My opinion
Right-sizing gets treated as a step backwards in a way that it simply isn't. A household with a smaller property, no mortgage stress and a healthy buffer is in a stronger position than one with a bigger property and no room to breathe.
The default, and frequently the correct one.
If the property still fits your life, the loan is comfortable, and you have no particular reason to move, then doing nothing is a real strategy — not an absence of one.
Worth checking while you hold: whether your mortgage is still on sensible terms and rates. Owners often stay on a package well past the point where refinancing or repricing would have been sensible, simply because nothing forced them to look.
The path that gives owners the best of both worlds. But let us look at the nuances of decoupling before jumping into it.
Things to look out for:
The test I would apply
Are you 100% certain that you will not be selling your EC in the next 4 years (current SSD holding period)? If the answer is no, then this might be a hefty hidden cost that most owners don't foresee themselves paying.
Could you service both properties for twelve months with no rental income at all? If the answer is no, then your plan depends on a tenant you have not met yet.
Holding period as at September 2026. The SSD schedule has been revised before, and which version applies depends on when the share was acquired — check the current position with IRAS.
Some households pass that test comfortably. For them, a second property can be a reasonable long-term position. The point is that it should be a decision made against the test, not a projection.
I would not sell because the MOP is up and all my neighbours are doing it. I would not buy a second property on the strength of a rental projection alone. And I would not make any of these decisions before doing up the numbers and backtest against it.
Last updated 29 September 2026Based on publicly available Singapore property data
Sources & where to verify
Rules, rates and published figures change. Check the current position on the official source before you act on anything here.
New insights, when they're worth sending
Occasional emails when I publish something useful. No listings, no blasts.
Where most people go next from here.
I'd like to measure which articles are actually useful, using Google Analytics and a Meta advertising pixel. Nothing is loaded until you choose, and declining costs you nothing on this site. What these do.